Last reviewed: October 2026
You hold FHA DE and VA SAR, you clear conditions before lunch, and you can tell from page one of a 1040 whether the self-employed borrower is going to need a second year of returns. Then you search "remote mortgage underwriter jobs" and LinkedIn promises more than 1,000 openings. Scroll the first 60 and you find two commercial underwriters at BMO, three consumer-loan desks, a manufactured-home dealer channel, a multifamily agency shop and a processor role mixed in with the real seats.
The usual line is that underwriting is desk work, so remote seats are everywhere. That's technically true and practically misleading. The real listings are far fewer than the counter suggests, and the ones that let you work from home cluster at one kind of lender: the kind whose payroll swings hardest when rates move. And the "temporary DE underwriter, work from home" gig a lot of underwriters picture runs straight into an FHA rule.
Get Remote Job Tips in Your Inbox
Weekly strategies, salary data, and new opportunities
Unsubscribe anytime. No spam.
We analyzed 165 residential mortgage underwriter job postings across 139 employers, first listed between February and October 2026, after setting aside the insurance, commercial, multifamily, title and consumer-loan postings that share the title. Fifty-five are fully remote. What decides which 55 is a question most postings never ask out loud: who keeps the loan after you approve it?
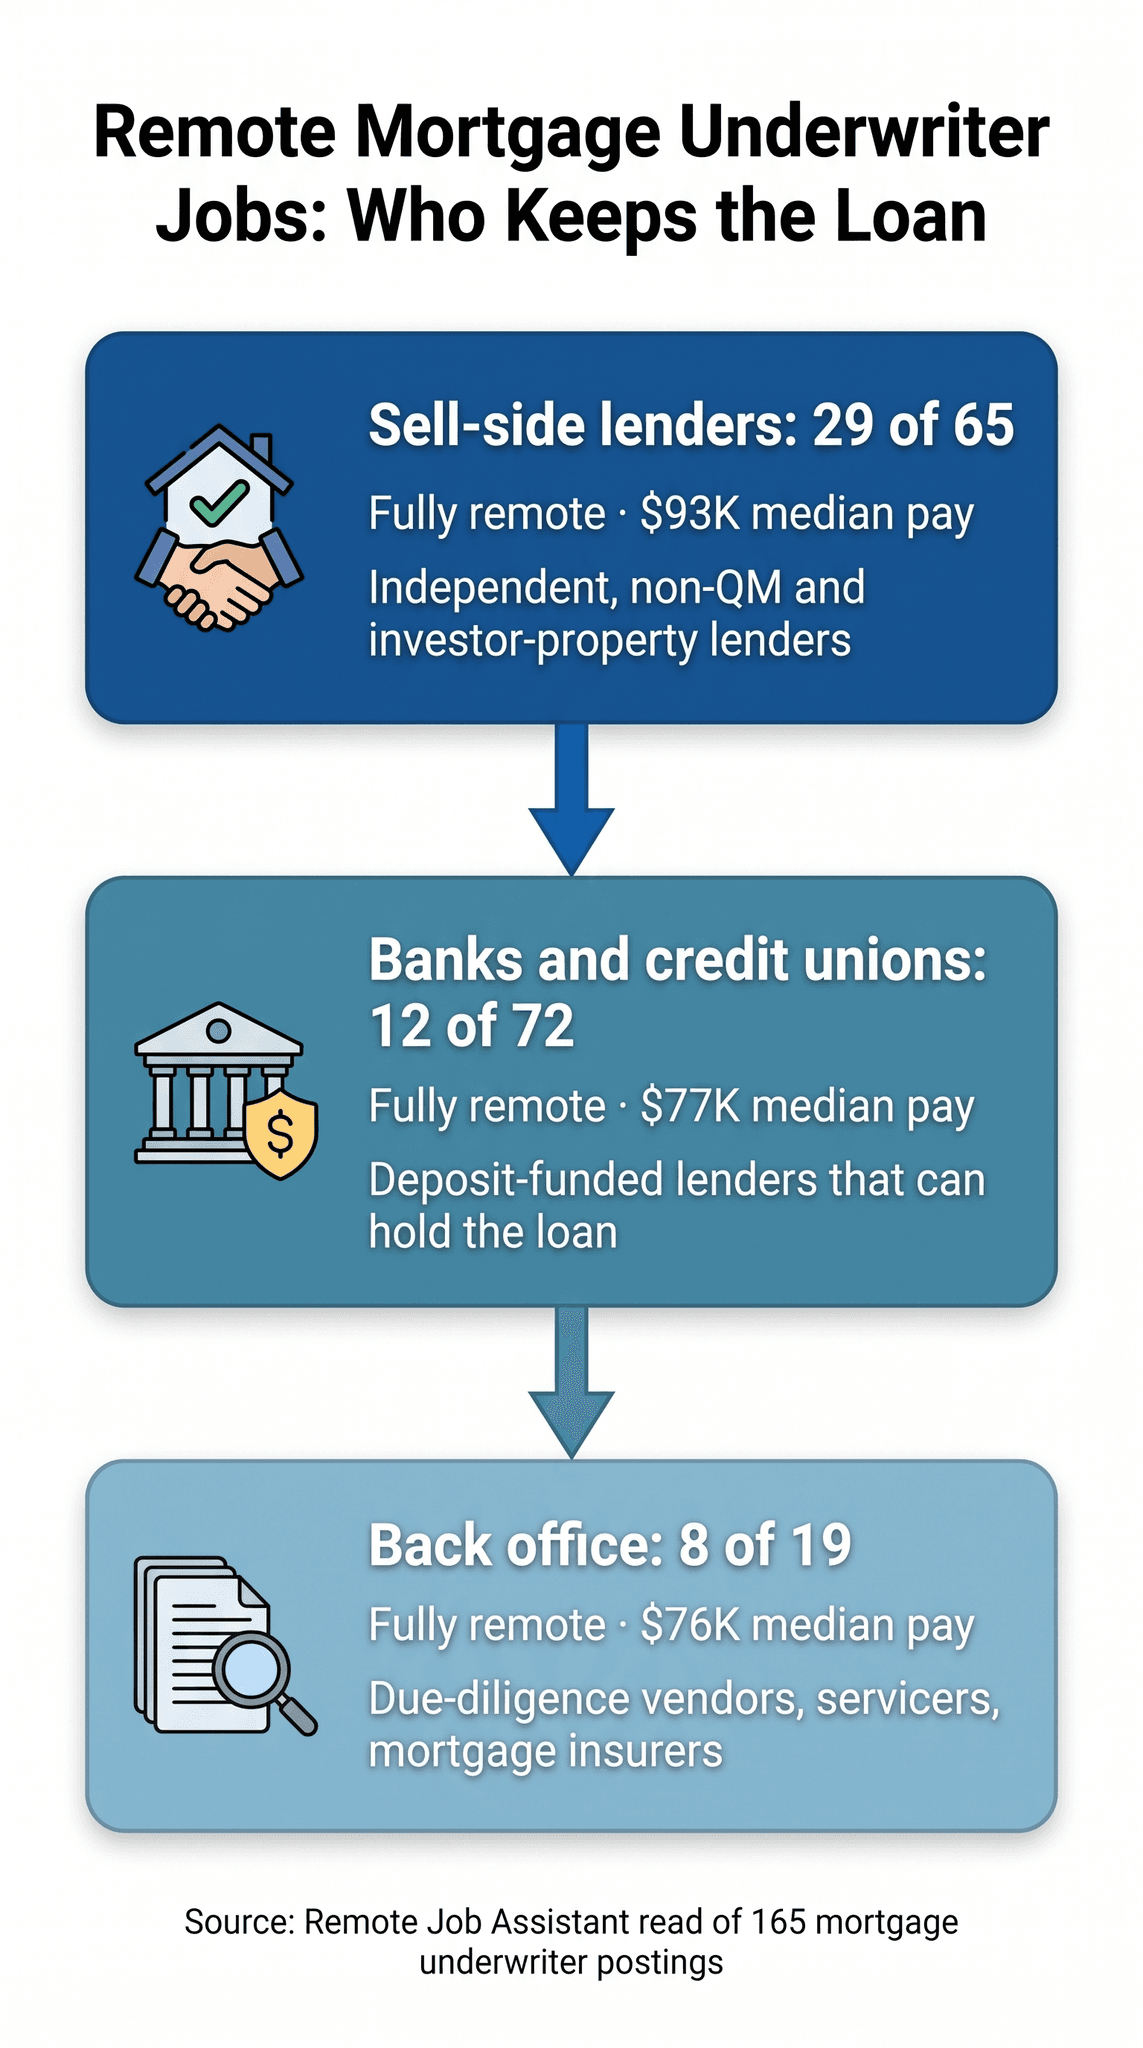
Yes, mortgage underwriting is one of the more remote jobs in lending: 55 of the 97 postings that state a work model are fully remote. But those seats sit mostly with lenders that sell their loans (29 of 65 fully remote) rather than banks and credit unions (12 of 72). They pay more, not less. And they belong to the part of the industry whose payroll fell 39% after 2021.
Here are the numbers behind that answer, each with its denominator.
Based on 165 residential mortgage underwriter postings at 139 employers (February to October 2026):
- 55 of 165 (33.3%) are fully remote; that is 55 of the 97 postings that state a work model (56.7%), and 68 never say
- 29 of 65 sell-side lender postings are fully remote vs 12 of 72 at banks and credit unions; 42 of those 72 bank and credit-union postings name no work model at all
- $93K vs $77K median posted pay midpoint, sell-side (n=27) vs banks and credit unions (n=42); BLS puts loan officers, the occupation that includes loan underwriters, at $76,690 (May 2025)
- $95K vs $80K median midpoint when the posting names FHA DE or VA underwriting authority (n=18) vs when it doesn't (n=64)
- 5 of 165 postings are contract or temporary, and 0 of those 5 involve FHA, DE or VA work
- 30 of 82 posted pay ranges are hourly, with a median midpoint of $36.50 an hour
- 14 of 62 remote or remote-optional seats restrict your state, time zone or distance from an office
How We Collected This Data
On October 22, 2026, we pulled every mortgage underwriter posting we could read from four places: LinkedIn's public job search (1,089 result pages across 56 keyword searches plus a "mortgage underwriter" search in each of 51 state locations, 3,224 listing cards, 317 full job pages read), SimplyHired, which carries Indeed's listings (86 searches, 1,933 cards, 284 job pages), 37 bank and lender Workday career sites, and 48 Greenhouse, Lever, Ashby and SmartRecruiters boards. That gave us 838 underwriter-titled rows to classify.
We kept a posting only when its text describes residential mortgage underwriting. We set aside 95 insurance underwriting roles, 193 commercial, commercial real estate and multifamily roles, 42 title-insurance underwriting roles, 18 consumer-loan roles, 156 with no residential mortgage content, 20 first listed before 2026, and 12 by hand (loan originator roles, evergreen talent pools, commercial loans secured by real estate). The same employer and title posted in several cities or on several sites counts once; that collapsed 132 copies into the 165 that remain.
Work model comes from the posting text. Eight postings with silent text count as remote because the employer listed them remote: 7 carry Indeed's remote tag and 1 shows LinkedIn's country-only location. We checked that rule: all 21 LinkedIn postings with a country-only location and a second copy that states a work model were remote in that copy.
Pay medians use posted ranges only (82 of 165), at the range midpoint, with hourly rates annualized at 2,080 hours. Limits: Indeed, Glassdoor, ZipRecruiter and Reddit block automated reads, live postings lean recent (94 of 165 were first listed in September or October), and 68 postings state no work model, so remote shares are given both ways.
The Keep-or-Sell Test: Who Holds the Loan Decides Where You Sit
The Keep-or-Sell Test sorts a mortgage underwriting seat by what happens to the loan after you approve it. A sell-side lender sells it to investors within weeks. A keep-side lender, a bank or credit union funded by deposits, can hold it or service it. A back-office employer re-checks it after closing as a vendor, servicer or mortgage insurer. Each side has its own remote odds, pay band and exposure to the rate cycle.
The reason the test works is how the money moves. According to the Federal Reserve Bank of Richmond's August 2025 economic brief, nonbank mortgage companies fund loans held for sale on warehouse lines of credit that cover "the short period between the origination of a mortgage and the sale or securitization" of the loan. A lender living on that line has to turn files fast and sell them to Fannie, Freddie, Ginnie or private investors, so underwriting becomes a measured production line run to investor guides. A production line measured in files can be staffed from anywhere. Eleven of the 12 postings in our set that print a daily or monthly file count are sell-side.
Banks and credit unions fund loans from deposits. Their underwriters usually sit inside a consumer-lending department next to branch referrals, home-equity lines and portfolio exceptions, and they're paid on the institution's job grades. That's why 21 of 72 keep-side postings name home equity or HELOC work and 18 of 42 keep-side pay ranges are hourly.
Scoring a seat on the Keep-or-Sell Test:
- Sell-side seat (29 of 65 fully remote; 63.0% of the 46 that state a model; median pay $93K, middle half $81K to $100K, n=27). Independent mortgage lenders, non-QM and investor-property lenders, fintech lenders, builder-owned lenders. In the posting: wholesale, correspondent or TPO channels; non-QM named (31 of 65); a files-per-day number; Encompass; an NMLS ID in the company name.
- Keep-side seat (12 of 72 fully remote; 40.0% of the 30 that state a model; median pay $77K, middle half $70K to $92K, n=42). Banks and credit unions. In the posting: member or branch language, HELOC and home-equity products, hourly ranges, "Hybrid, must live locally," two or three office days, or no work model at all.
- Back-office seat (8 of 19 fully remote; median pay $76K, middle half $69K to $82K, n=11). Due-diligence and quality-control vendors (PLACE, Maxwell, ICE), outsourced fulfillment shops (Altisource, Mphasis, HCLTech), servicers (Carrington's loss-mitigation desk) and mortgage insurers. In the posting: "due diligence," "post-closing," "loss mitigation," "client," hourly pay (7 of 11). Its quality-control work is the only place contract labor can legally touch an FHA loan.
How to use it: read the posting for those signals before you read the title. If your household can't absorb a layoff in the next rate swing, target banks and credit unions and use DE to bargain for hybrid days; keep-side postings that name DE pay $92,500 (n=7) against $74,880 (n=35) for those that don't. If you want the remote seat and the top of the band, aim sell-side and ask about pipeline mix in the first call. If you want contract flexibility, aim back office.
| Keep-or-Sell tier | Postings (employers) | Fully remote, all postings | Remote, of those stating a model | Silent on work model | Median posted pay (n) | Hourly ranges | Printed file quotas |
|---|---|---|---|---|---|---|---|
| Sell-side | 65 (50) | 29 of 65 | 29 of 46 | 19 | $93K (27) | 4 of 27 | 11 |
| Keep-side | 72 (67) | 12 of 72 | 12 of 30 | 42 | $77K (42) | 18 of 42 | 1 |
| Back office | 19 (14) | 8 of 19 | 8 of 14 | 5 | $76K (11) | 7 of 11 | 0 |
The remaining 9 postings are staffing-firm reposts (8) and one community lender. The pattern holds at the employer level: independent mortgage lenders post 22 of 50 seats fully remote, banks 8 of 48, credit unions 4 of 24.
In mortgage underwriting, the remote premium is a cycle premium. The lenders most likely to let you work from home, and to pay you the most for it, are the ones whose headcount depends on next quarter's volume.
If you're aiming sell-side, timing matters as much as the resume: 94 of the 165 postings in this set were first listed in September or October, and the seats sit on dozens of separate career sites.
Stop Applying Manually
Our AI applies to hundreds of matching jobs while you sleep. Wake up to interviews, not more applications.
Where the 55 Remote Mortgage Underwriter Seats Are
By employer type, fully remote postings break down like this: independent mortgage lenders 22 of 50, banks 8 of 48, credit unions 4 of 24, vendors 5 of 11, servicers 3 of 4, investor-property lenders 4 of 7, fintech lenders 3 of 4, builder-owned lenders 0 of 4, mortgage insurers 0 of 4 (one more is remote-optional), and staffing reposts 5 of 8.
The sell-side employers say it plainly. Paramount Residential Mortgage Group tells its underwriter candidates that "we encourage remote Underwriting, and you can work for us from anywhere in the nation." Union Home Mortgage lists its TPO and non-QM underwriters as remote. Altisource calls its reverse-mortgage seat a "100% remote position." The keep-side exceptions exist, and they tend to come with a map.
Sell-side remote seats in our set: Paramount Residential Mortgage Group (DE Underwriter IV, Non-QM, team lead), Union Home Mortgage (TPO, non-QM), CrossCountry Mortgage (condo underwriter, Pacific hours), Village Capital (FHA Streamline and VA IRRRL), Deephaven (non-QM), Mutual of Omaha Mortgage and Longbridge Financial (reverse), Atlantic Coast Mortgage (jumbo and non-QM), American Pacific Mortgage, Change Lending, Visio Lending and New Silver (investor property), Upstart and Knock.
Keep-side remote seats: SouthState Bank (remote in eight named states), Capital Bank ("This is a 100% remote role"), Zions ("within the Zions Bancorporation footprint"), First Citizens, Trustmark, Texana Bank, Pathward, Golden 1 Credit Union, Keesler Federal Credit Union, San Francisco Federal Credit Union and Quorum Federal Credit Union.
Back-office remote seats: PLACE and Maxwell (due diligence), Altisource (fulfillment, including reverse), Carrington (loss mitigation).
Silence is the bigger signal on the keep side. Of 72 bank and credit-union postings, 42 never mention a work model, and among the 30 that do, hybrid (12) ties fully remote (12). Hybrid usually means three office days: of the 20 hybrid postings in the whole set, 7 name the days, and 6 of those 7 ask for three or more. A bank that expects you in the office three days a week often doesn't think to say so. Read a silent bank posting as an office job until a recruiter tells you otherwise.
"Remote" also comes with strings. Fourteen of the 62 remote or remote-optional postings limit where or when you can work: Visio Lending lists 15 "Authorized Remote Locations," American Bancshares Mortgage says "Fully Remote (Florida Residents Only)," Quorum excludes Montana, Nebraska, Rhode Island and Puerto Rico, Anza Mortgage Insurance opens remote work to seven western states, and CrossCountry and Union Home tie their seats to Pacific time. AD Mortgage turns distance into the rule: "Candidates within a 50-mile radius of either office will be expected to work onsite."
A few more traps show up in the posting text itself:
- Remote after the first weeks. Newtown Savings Bank's seat "is REMOTE after onboarding is complete, however candidates must live within commuting distance to Newtown, CT, and will be required to visit the office for training, meetings, etc." We count it as hybrid.
- Hybrid you have to earn. Mphasis's Boca Raton seat says: "To qualify for Hybrid, candidates are required to achieve and maintain documented performance metrics."
- Staffing reposts. 8 of the 165 postings came from staffing firms, and one that surfaces in remote searches says "PLEASE NOTE, THIS IS NOT A REMOTE ROLE."
- Hours, not just location. American Pacific Mortgage's remote seat prefers the Midwest to the East Coast "as this resource would be required to work East Coast hours."
- Seats that don't exist yet. We set aside 2 "general interest" and "future opportunities" postings that collect resumes for openings that aren't open.
Why the split? A lender that sells every loan underwrites to investor guides that any approved underwriter can read from a home office, and it hires wherever the experience is. A bank underwriter also handles portfolio exceptions and branch questions, and the bank's job architecture was built around buildings. If you want the broader map of which mortgage jobs need an NMLS license and which don't, our guide to remote mortgage jobs covers the License Line; live finance listings show what's open this week.
What Remote Mortgage Underwriters Earn
Pay figures here come from the 82 of 165 postings that publish a range, taken at the midpoint, with hourly rates annualized at 2,080 hours and cross-referenced with the BLS May 2025 wage data. Ranges move with the market, so use them as bands, not offers.
| Group | Posted ranges | Median midpoint | Middle half |
|---|---|---|---|
| Sell-side lenders | 27 | $93K | $81K to $100K |
| Banks and credit unions | 42 | $77K | $70K to $92K |
| Back office (vendors, servicers, MI) | 11 | $76K | $69K to $82K |
| Junior underwriters | 6 | $64K | $60K to $72K |
| Mid-level underwriters | 47 | $82K | $72K to $92K |
| Senior underwriters | 20 | $90K | $76K to $95K |
| Underwriting managers and leads | 8 | $107K | $72K to $123K |
| Postings naming FHA DE or VA authority | 18 | $95K | n/a |
| Postings naming neither | 64 | $80K | n/a |
Three things stand out.
First, remote doesn't cost you money here. Fully remote postings have a median midpoint of $92.5K (n=29) against $83K for hybrid (n=14) and $82.5K on site (n=11). Inside the sell side the gap is wider: $100K remote (n=13) vs $80K on site (n=5). That follows from the Keep-or-Sell Test: the employers most willing to hire remotely also pay the most.
Second, a lot of this work is paid by the hour. Thirty of the 82 posted ranges are hourly, with a median midpoint of $36.50 an hour and a middle half of $31.00 to $41.55. That's 18 of 42 keep-side ranges against 4 of 27 sell-side. Ten postings say outright that the seat is non-exempt or overtime-eligible; Visio Lending lists "Non-Exempt/Hourly/Overtime Eligible."
Third, government files pay. Postings that name FHA, VA or USDA lending have a median midpoint of $92.5K (n=33) against $79K for postings that name none (n=49). The low end is home equity at $75K (n=18) and loss-mitigation underwriting at servicers, where Carrington posts its Underwriter I seat at $23 to $26 an hour.
For context, the BLS Occupational Outlook for loan officers, the occupation BLS uses for loan underwriters, puts the May 2025 median at $76,690, with the top tenth above $153,180. Keep-side midpoints sit right on that median; sell-side midpoints sit about $16,000 above it. If your target is six figures, 11 of the 14 postings with a midpoint of $100K or more were manager, senior or DE seats, so filter remote jobs paying $100K-plus with that in mind; most mid-level underwriters land in the $75K-plus band.
The pay gap is where most underwriters stop reading. The credential that moves it is the next thing to check.
Stop Applying Manually
Our AI applies to hundreds of matching jobs while you sleep. Wake up to interviews, not more applications.
The DE Premium: Pay That Moves With You, Approval That Doesn't
FHA Direct Endorsement shows up in 44 of 165 postings (26.7%): required in 12, preferred in 24, mentioned in another 8. Read that split before you skip a posting: two-thirds of the DE asks that say either way are preferences, so a strong conventional underwriter without DE should still apply. VA underwriting authority, SAR or LAPP appears in 36 of 151 production postings. Where either is named, the median posted midpoint is $95K (n=18) against $80K (n=64) where neither is. The premium shows up on both sides of the Keep-or-Sell Test: $97,500 vs $88,750 inside the sell side (n=7 and n=20), $92,500 vs $74,880 inside banks and credit unions (n=7 and n=35).
DE doesn't shrink your remote options, either. Among production postings that state a work model, 18 of 28 DE-naming seats are fully remote (64.3%), against 30 of 59 that don't name DE (50.8%).
DE is the rare credential that raises your pay without shrinking your remote options.
The reason it pays is written into the rule. HUD Handbook 4000.1, in its August 12, 2026 issue, says Direct Endorsement approval "permits a Mortgagee to underwrite Title II Single Family Mortgages without FHA's prior review." A lender can only close FHA loans on its own authority if it employs underwriters who hold the designation, and it can't borrow them.
The federal rules behind the DE and VA premium:
- FHA DE eligibility. HUD Mortgagee Letter 2025-16 requires three years of experience reviewing credit applications and one- to four-unit appraisals within the past five years (or two in the past three plus three more in the past ten), employment with "a single Mortgagee," and authority to bind it. It dropped the full-time requirement on June 27, 2025, so part-time DE seats are now allowed, but "Mortgagees must continue to ensure their DE underwriters are permanent employees of a single Mortgagee and underwriting functions are not contracted out."
- VA underwriter approval. VA Circular 26-24-1 (January 18, 2024) has the lender nominate you on VA Form 26-8736a with a $100 fee. You need three years of processing, pre-underwriting or underwriting with one year of VA decisions in the past three, or a current MBA Certified Residential Underwriter designation. "Previous approval as a VA-approved underwriter for a former lender does not automatically transfer to a new lender."
- VA SAR. VA's SAR guidance requires a full-time salaried employee with three years of appraisal-review experience; three years as an FHA underwriter meets it.
Those rules have a practical edge for a remote move. Your experience and your CHUMS number travel with you; the employment tie doesn't. DE requires a job with a single mortgagee, and VA approval has to be nominated again by each new lender. Five postings in our set name the CHUMS ID, so put it on the first line of your resume next to SAR status. If you're coming from insurance underwriting, our guide to remote underwriting jobs lays out how the two professions differ before you invest the three years DE requires.
Contract and Temp Underwriting: Where It Legally Lives
Only 5 of the 165 postings are contract or temporary, and none involves FHA, DE or VA work. Two are post-close due diligence: PLACE and Maxwell each post a remote "Contract Due Diligence Underwriter." Quorum Federal Credit Union runs a remote "Temporary Mortgage Underwriter - Correspondent Loans" at $36.05 to $40.85 an hour, which annualizes to about $80K at the midpoint, $15K under the DE band. Native Community Capital posts a remote contract underwriter at $50 to $75 an hour. Unison's contract seat underwrites home equity investments, not mortgages, and is hybrid.
That isn't an accident of our sample. The same HUD Handbook 4000.1 lists "Quality Control" and "Third Party Verification" among the functions a lender may hand to contractors, then says: "A Mortgagee must not contract out management or underwriting functions." It also bars paying underwriting and QC staff on commission. On conventional loans there's more room: Fannie Mae's Selling Guide lets a lender contract underwriting help from "a third party known for the quality of its underwriting (such as a mortgage insurer)." That is the opening for contract underwriting on conventional files; FHA has no equivalent.
A contract underwriter can re-check an FHA loan after it closes; HUD says no contractor can underwrite one before it does.
If you want 1099 or temp flexibility, aim at due-diligence firms and QC vendors and expect hourly or project-based pay. If you want the $95K band, keep a W-2 seat that uses your DE. Quality control also opens a lateral path: underwriters who spend a few years in post-close review often move into the work covered in our remote compliance jobs guide.
The Production Math: Files per Day
Twelve of 165 postings print a number, and 65 use production, turn-time or service-level language without one. The numbers that exist are blunt:
- Union Home Mortgage: "a minimum of 4 new loans per day for government underwriters and 6 new loans per day for conventional underwriters," and "3+ new loans per day" on non-QM
- Paramount Residential Mortgage Group: "3 Underwriting decisions/day" on DE and conventional seats, "2 decisions/day" on non-QM
- Capital Bank: "a minimum of three new loan files per day"
- American Pacific Mortgage: "a minimum of 2 loans per day"
- Acrisure Mortgage, non-QM: "approximately 25–35+ loans per month"
- Deephaven, non-QM: "50+ initial underwrites per month"
Read the quotas by the kind of file you want to spend your day on:
| If you want | Look at | What the postings print |
|---|---|---|
| Fewer, harder files | Non-QM desks at sell-side lenders | PRMG 2 decisions a day; Acrisure 25 to 35+ a month; Deephaven 50+ a month |
| Government files under your DE | Government desks at sell-side lenders | Union Home at least 4 new loans a day; PRMG 3 decisions a day |
| Higher-volume conventional | Conventional desks | Union Home 6 new loans a day |
| No printed number | Banks and credit unions | 1 of 72 keep-side postings prints a quota |
Two patterns are worth knowing before you negotiate. At Union Home, a government file carries a lower daily count than a conventional one, and the non-QM counts at PRMG, Acrisure and Deephaven run lower still, because bank-statement income, asset depletion and DSCR math take longer to clear. And the quotas are a sell-side habit: 11 of the 12 come from lenders that sell their loans, which fits the Keep-or-Sell Test. When every funded loan sits on a warehouse line until it's sold, the lender measures the whole pipeline in files, including yours.
Schedules come with the seat too. Essent asks its mortgage-insurance underwriters for "overtime and weekend work when needed to support Essent turn-time service level agreements." CrossCountry's condo seat "primarily operates within Pacific Time zone working hours," Canopy Mortgage requires you to be "located in either the Eastern or Central timezones," and Orion Lending makes "Time zone alignment with the assigned UW team" a "condition of employment." Ask for the quota on the first call, and ask what the team's average daily decision count was this quarter against the same quarter last year. Then divide the salary by the quota; two seats at $90K are not the same job at 3 files a day and 6.
Once you know the quota you'll accept, apply widely: in our set, the 55 remote seats came from 43 different employers.
Stop Applying Manually
Our AI applies to hundreds of matching jobs while you sleep. Wake up to interviews, not more applications.
Rates, Layoffs and Choosing Your Side
The cycle shows up in federal payroll data. BLS employment in real estate credit, the industry where nonbank mortgage lenders sit, peaked at 293,000 in June 2021, fell to 185,600 by December 2023, and stood at 178,100 in August 2026 (preliminary): down 114,900, or 39.2%. Over the same stretch commercial banking employment slipped 1.4% (1,367,100 to 1,347,500) and credit-union employment rose 15.6% (282,800 to 326,800). Meanwhile Freddie Mac's mortgage rate survey has the 30-year fixed going from 5.98% on February 26, 2026 to 7.40% on October 8 and October 15, the year's high.
The employers most likely to offer a fully remote seat at the top of the pay band are the same ones whose underwriting payroll fell 39% after 2021. Refinance demand rises and falls with rates, and a lender that lives on a warehouse line staffs to volume. A remote sell-side seat is a good job with a shorter fuse.
That doesn't mean avoid the sell side. It means choose with your eyes open:
- If you have DE and need stability more than a home office, aim keep-side. Expect hybrid more often than remote and a median around $77K, higher with DE ($92,500, n=7).
- If you want the remote seat and the top band, aim sell-side, and ask how much of the pipeline is purchase vs refinance, how big the underwriting team was at the start of 2024 compared with now, and whether underwriters cross-train into QC or loss mitigation when volume drops.
- If you want contract or project work, aim back office and price your hours against the $36.50 median hourly midpoint.
- If you're early in your career, take the office seat. None of the 10 junior postings in our set is fully remote, the junior median is $64K (n=6), and the median posting asks for 4 years of experience. An in-office seat that puts government files in front of you is the shortest road to DE eligibility, and DE is what moves you into the remote band.
If you're weighing a bank against an independent lender on benefits as much as pay, our remote banking jobs guide covers the keep-side employers in more depth.
How to Get Hired as a Remote Mortgage Underwriter
The postings tell you what they screen for. Of 165, 95 mention appraisal review, 56 name Encompass, 48 name DU, LPA or automated underwriting, 45 ask for self-employed income or tax-return analysis, 32 mention fraud, 21 ATR/QM, 15 manual underwriting and 14 condo review. Of the 101 that state years of experience, the median ask is 4; 47 ask for 5 or more and 26 accept 2 or fewer.
Work through it in this order:
- Put your authority on line one. DE with your CHUMS ID, VA approval or SAR/LAPP status, delegated conventional authority. Five postings name the CHUMS ID outright.
- Then your throughput and mix. Files per day and the split across government, conventional, jumbo and non-QM, because that's how sell-side shops will size you against a 3-to-6-a-day quota.
- Then systems. Encompass, DU, LPA, in the posting's own words.
- Under 4 years of experience? Apply keep-side and in-office first. None of the 10 junior postings in our set is fully remote, and an office seat with government files is the shortest road to DE.
- Before the first call, find the location line and the quota line. If the posting has neither, ask for both before you talk salary.
"DE underwriter (CHUMS ID on request) clearing 4 to 6 files a day across FHA, VA and conventional purchase loans in Encompass; manual underwriting, condo review and self-employed income analysis." Every phrase comes from the posting language counted above.
Interviews have their own rules now: Acrisure tells non-QM candidates that "Applicants must complete all interviews without the use of AI or automated tools," and Top Tier Federal Credit Union says AI-prepared application materials "will not be considered."
Then go wide. The 55 remote seats in this set came from 43 employers, most of them sell-side lenders, spread across separate applicant systems: CrossCountry, Movement, Deephaven and SouthState post through Workday; PLACE, Maxwell, Upstart, Knock and Pathward through Greenhouse; Altisource and Longbridge through SmartRecruiters. Sell-side seats also move with volume. That's the case for an auto-apply service built for remote job searches: it gets your resume in front of the independent lenders while their pipeline is still full. If applications aren't turning into calls, why you're not getting interviews walks through the screening failures, and the finance and accounting job category collects the adjacent credit and QC roles.
Frequently Asked Questions
I have FHA DE and VA SAR. Can I find a remote mortgage underwriter job, and where should I look first?
Yes. Start with independent and non-QM lenders: 29 of 65 sell-side postings in our 2026 set were fully remote, against 12 of 72 at banks and credit unions. DE doesn't cost you remote options; 18 of 28 DE-naming production postings that state a work model were fully remote. Expect location strings on some of them, such as state lists or a required time zone.
Can I work as a contract or temp DE underwriter from home?
Not on FHA files. HUD Mortgagee Letter 2025-16 says DE underwriters must be permanent employees of a single mortgagee and that underwriting functions are not contracted out, and HUD Handbook 4000.1 allows lenders to contract out quality control but not underwriting. In our data, 5 of 165 postings were contract or temporary and none involved FHA, DE or VA work; the remote contract seats were in post-close due diligence.
How much do remote mortgage underwriters make in 2026?
Fully remote postings had a median posted midpoint of $92.5K (n=29). Sell-side lenders posted a median of $93K (n=27) against $77K at banks and credit unions (n=42), and 30 of 82 posted ranges were hourly with a median midpoint of $36.50. BLS puts loan officers, the occupation that includes loan underwriters, at a $76,690 median.
Is a bank or an independent lender better for a remote underwriting career?
It depends on which side of the Keep-or-Sell Test you can live with. Independent lenders post more remote seats and pay more, but BLS employment in real estate credit, where nonbank lenders sit, is 39.2% below its June 2021 peak. Commercial banks are down 1.4% and credit unions up 15.6% over the same period.
How do I score a posting on the Keep-or-Sell Test before I apply?
Look for the signals. Wholesale, correspondent or TPO channels, non-QM products, a files-per-day number and an NMLS ID in the company name mean sell-side. Member or branch language, home-equity products, hourly ranges and hybrid days mean keep-side. Due diligence, post-closing, loss mitigation and client language mean back office.
Does my VA underwriter approval transfer if I switch lenders?
No. VA Circular 26-24-1 says approval for a former lender "does not automatically transfer to a new lender"; the new lender must nominate you, with a $100 fee per nominee. You need three years of processing or underwriting experience including one year of VA decisions in the past three, or a current MBA Certified Residential Underwriter designation.
How many loans a day will a remote mortgage underwriter be expected to clear?
Where postings print a number, it runs from 2 to 6 new files a day. Union Home Mortgage asks government underwriters for at least 4 and conventional underwriters for 6, and Paramount Residential Mortgage Group sets 3 decisions a day on DE and conventional files and 2 on non-QM. Eleven of the 12 printed quotas came from lenders that sell their loans.
Start Your Remote Mortgage Underwriter Search
Decide your side of the Keep-or-Sell Test before you apply, lead with your DE and VA authority, and read the quota and the location line before the salary. The sell side has the remote seats and the top band; the keep side has the steadier payroll; the back office has the contract work.
For the broader picture, our remote underwriting jobs guide separates mortgage from insurance underwriting, and the remote mortgage jobs guide maps which mortgage roles need an NMLS license. Current remote finance openings update daily, and Auto-Apply gets you onto the sell-side lenders' career sites while they're still hiring.
A loan file reads the same from a spare bedroom as from a branch office. Who's paying to hold the loan until it sells decides which one you get.
Ready to Find Your Remote Job?
Browse thousands of curated remote jobs or let AI apply for you.
Browse Remote JobsRelated Job Guides
Remote Medical Director Jobs: 305 of 1,860 Are Remote
We read 1,860 medical director job postings: 305 are fully remote, mostly health plan and pharma seats. See which go home, what they pay, and the license rules.
31 min read
Remote Clinical Pharmacist Jobs: 74 of 1,587 Are Remote
We read 1,587 clinical pharmacist postings. 74 are fully remote, mostly payer and PBM claim review. See which seats go home, their pay and the license catch.
29 min read
Remote Epidemiologist Jobs: 1 of 44 Public Seats Is Remote
We read 138 epidemiologist job postings: 15 are remote, and only 1 of 44 at health departments. See who hires remote epis, what they pay, and how to get there.
26 min read